PayID Casino – Instant Deposits & Fast Withdrawals
Explore the practical side of PayID casino payments: what to check before sending Australian dollars, how a cashout moves through the system, and which account details deserve a second look.
 Explore deposits, withdrawals and payment safety in Australia.
What would you like to understand?
Follow the payment journey, or start with Australian rules and safety.
Quick AI Summary: PayID Casinos (TL;DR)
- Payment route: A recognisable identifier points to a bank account.
- Credit timing: Allow for both the transfer and the receiving account update.
- Cashout timing: Separate operator approval from the movement of released funds.
- Recipient check: Review the name displayed by your bank before confirmation.
A payment option is only one part of evaluating an online casino. This guide separates the PayID transfer itself from the operator’s account rules, giving readers a clearer way to examine deposits, cashouts and the information displayed in a cashier.
Rather than treating every fast-payment claim as a promise, look at each stage individually. The bank may complete its part quickly while the receiving service still needs to match a reference, review an account or approve a withdrawal.
| PayID Casino Australia – Read the briefing 2026 | |
|---|---|
| 🎯 Payment Method | PayID (Australian Real-Time Osko Payment System) |
| ⚡ Deposit Speed | Instant (Under 60 seconds) |
| 💸 Withdrawal Speed | 1–24 hours (some top casinos process instantly) |
| 🏦 Supported Banks | 100+ AU Institutions (CommBank, NAB, ANZ, Westpac, ING, etc.) |
| 💰 Transaction Fees | Zero fees (100% free transfers) |
| 🔒 Security Level | Bank-grade encryption & 2FA authentication |
| 📱 Availability | 24/7/365 (Instant processing on weekends & public holidays) |
| 💵 Supported Currency | AUD (Australian Dollars only) |
| 📊 Min/Max Limits | Varies by casino (Typically $10 to $10,000 per transaction) |
| 🎰 Casino Acceptance | Growing rapidly – Accepted at over 100+ offshore online casinos |
One payment. Separate checkpoints.
A bank transfer, an account credit and a withdrawal approval are different events. Select a stage to explore its guide.
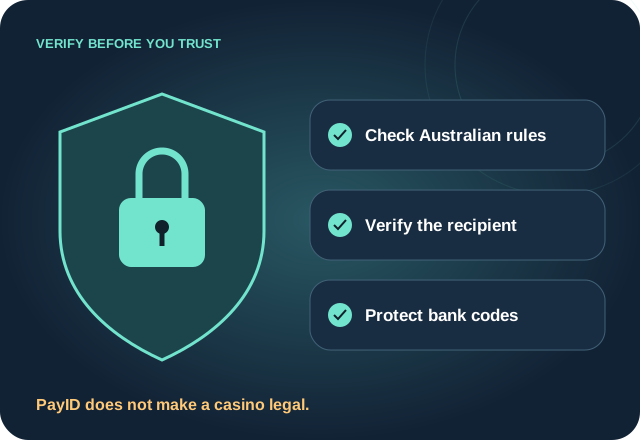
A payment option does not establish that a gambling service is lawful in Australia.
What is a PayID Online Casino?
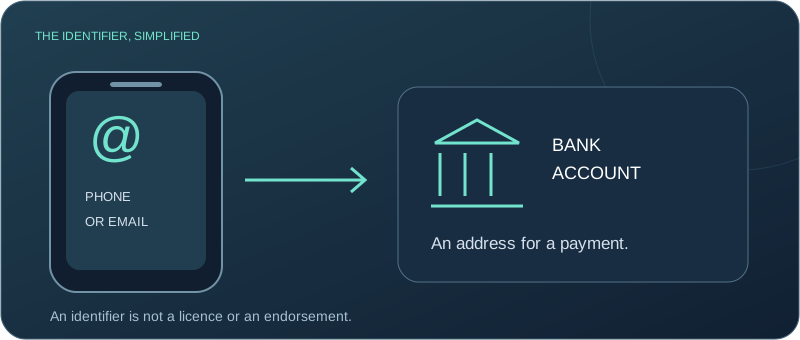
The expression PayID casino describes a gambling website that lists PayID among its banking options. The payment identifier and the gambling service are separate: accepting a bank transfer does not establish the quality of the operator.
An email address or mobile number can serve as a recognisable payment identifier. Before authorising a transfer, compare the recipient name shown by your bank with the details supplied in the cashier and check any required reference.
How PayID Works at Online Casinos
Think of the payment journey as a sequence: recipient lookup, bank authorisation, transfer and account reconciliation.
- Prepare the identifier: Open your bank’s settings and choose the account to associate.
- Read the cashier: Confirm the available route and its instructions.
- Match the instruction: Check the destination, amount and payment reference.
- Authorise securely: Use your bank’s own confirmation screen.
- Check receipt: Keep the confirmation until the receiving balance is updated.
Benefits for Australian Players
For readers comparing payment options, the useful questions concern identification, availability, charges and the time taken to credit an account.
- Less retyping: An identifier can be easier to recognise than account digits.
- Private credentials: Keep passwords and approval codes within your banking session.
- Familiar interface: Review the transfer through your existing bank app.
- Out-of-hours checks: Distinguish network availability from staff review times.
- Visible charges: Read the fee information before sending money.
PayID vs Traditional Banking Methods
| Comparison point | PayID route | Standard transfer | Card payment |
|---|---|---|---|
| Time until deposit credit | Example: less than one minute | Example: 1–3 working days | Example: immediate–24 hours |
| Cashout estimate | Example: 1–24 hours | Example: 3–5 working days | Example: 3–7 working days |
| Possible charges | Check for charges | See account terms | Example quoted: 2–5% |
| Information entered | Registered phone or email | Routing and account digits | Card credentials |
| Operating window | Network available beyond office hours | Processing schedule varies | Check provider availability |
Best Online Casino PayID Withdrawal – How It Works
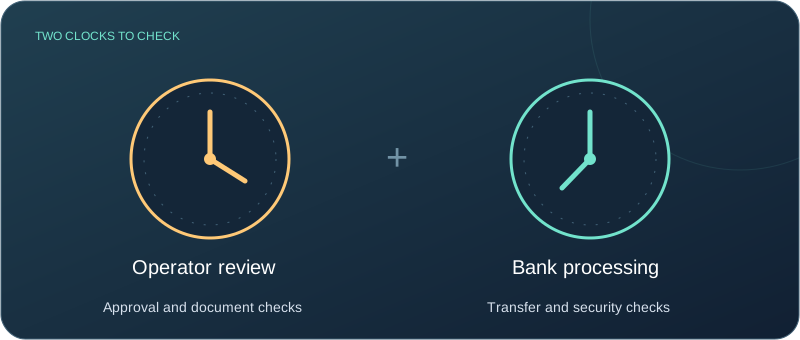
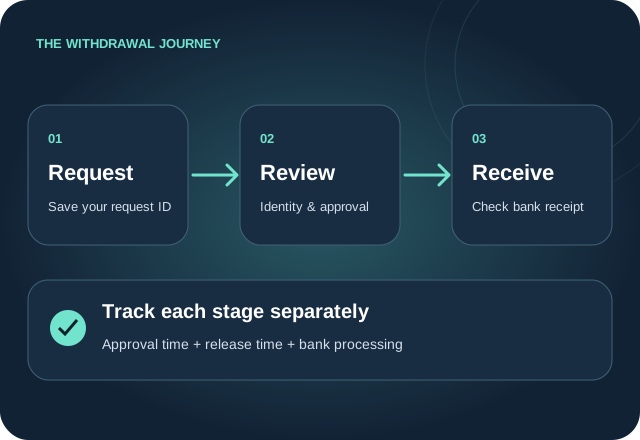
A withdrawal has two clocks: the operator’s review period and the bank transfer that follows. Published payout estimates should explain both. An account check, incomplete document request or payment mismatch can extend the overall wait.
Step-by-Step Withdrawal
- Open the account: Locate the withdrawal area in the cashier.
- Check the route: Confirm PayID is offered for receiving funds.
- Review the amount: Compare the request with the permitted range.
- Identify the destination: Supply the identifier associated with your account.
- Inspect the summary: Recheck the destination and requested sum.
- Allow for review: Complete any legitimate account-verification steps.
- Confirm arrival: Match the bank credit with the withdrawal record.
PayID Withdrawal Timeframes
| Illustrative review category | Example overall wait |
|---|---|
| Shorter review window | Example: below two hours |
| Mid-range review window | Example: six–twelve hours |
| Longer review window | Example: one–two days |
| Initial account review | Example: 1–3 working days for checks |
Tips for Faster Cashouts
- Prepare documents: Resolve outstanding identity checks before requesting payment.
- Read offer conditions: Check whether promotional restrictions affect the available balance.
- Match ownership: Use payment information that complies with the account-holder policy.
- Read service conditions: Do not assume a membership tier guarantees faster payment.
- Check review hours: Look for a published schedule for manual approvals.
General Withdrawal Limits
The figures below are examples from the supplied article, rather than confirmed limits for a particular operator. Read the current cashier policy before relying on an amount.
- Illustrative request floor: AUD 10–50; confirm the actual minimum.
- Example daily range: AUD 5,000–10,000; operator conditions apply.
- Example weekly range: AUD 20,000–50,000; verify the remaining allowance.
- Example monthly range: AUD 50,000–100,000; check the applicable policy.
- Account-specific caps: Obtain written terms for any individually agreed limit.
Advantages of PayID Casinos Online
A useful banking comparison starts with the full journey, rather than a headline speed claim. Consider what the bank displays, what information the receiving service requests and how a transaction will appear in your statement.
Lightning-Fast
A fast bank transfer does not guarantee an equally fast account update or cashout approval.
Bank Security
Use the authentication controls offered by your bank and keep access credentials private.
Zero Fees
Check both the cashier terms and your account’s fee schedule before authorising a payment.
24/7 Processing
Network availability and the operator’s staffing hours are different parts of the process.
Key Advantages Explained
01 / A shorter route through the payment screen
Convenience comes from fewer details to enter and a familiar banking interface. The receiving service still needs to identify the payment correctly, so a missing reference can matter as much as the transfer speed.
02 / Recognisable details, careful checks
A recognisable identifier can reduce the need to type account numbers. It does not make a recipient trustworthy by itself: review the displayed name and avoid sharing login details, security codes or remote access to your device.
03 / Look at the complete cost
Compare the amount leaving your account with the amount expected at the destination. A payment method’s fee structure does not automatically cover operator charges, account fees or currency conversion.
04 / Understand the two operating clocks
A payment network may remain available outside office hours while an operator’s manual review queue waits for staff. Keep that distinction in mind when comparing weekend cashout estimates.
Additional Benefits
- Bank-managed setup: Look for identifier registration in your existing account settings.
- Recognisable details: Check the identifier carefully, including its spelling.
- Traceable receipt: Save the confirmation and transaction reference.
- Authentication controls: Follow your bank’s approval process without sharing codes.
- Currency review: Confirm whether the requested and credited amounts are both in AUD.
- Spending visibility: Reconcile account activity against a budget you set beforehand.
How to Deposit and Withdraw at PayID Casino
The steps below outline two different tasks: setting up a bank identifier and using payment instructions supplied by a service. Follow the actual prompts in your bank and cashier, as wording and availability can differ.
Setting Up PayID with Your Bank
Begin in your own bank’s app or website and locate its identifier-management settings:
- Sign in securely: Open the banking app directly on your own device.
- Find identifier controls: Look under payments or account-management settings.
- Start registration: Select the option to add a payment identifier.
- Choose a contact detail: Use a supported email address or phone number you control.
- Associate an account: Select the eligible destination account.
- Confirm ownership: Follow the bank’s contact-verification prompts.
- Check status: Wait for the bank to confirm that setup is complete.
Your bank’s own help pages are the appropriate place to confirm account eligibility, supported identifiers and activation steps.
Making Your First Deposit
When reviewing a deposit instruction, work through the details in this order:
- Review the service: Understand its account conditions before registration.
- Locate payments: Open the deposit panel within the account.
- Inspect supported methods: Confirm PayID appears for your account and currency.
- Choose a sum: Stay within your personal budget and the displayed limits.
- Read the destination: Note the recipient identifier and required reference.
- Open your bank separately: Start a payment from the bank’s own app.
- Match every field: Copy the exact recipient and reference from the instruction.
- Review before approval: Compare the recipient name and amount on the bank screen.
- Retain evidence: Save the receipt and wait for the account credit.
Withdrawal Process Step-by-Step
For a cashout request, check the destination details and account conditions before submitting:
- Resolve conditions: Check available balance, identity status and offer restrictions.
- Open cashouts: Find the account’s withdrawal request panel.
- Inspect the method: Verify that PayID is listed for outbound payments.
- Supply the destination: Enter the identifier linked to an eligible account you control.
- Set the request: Choose a sum within the published withdrawal allowance.
- Read the final screen: Check the identifier, amount and any disclosed charges.
- Send the request: Retain the confirmation number after submission.
- Track the review: Watch for account messages about approval or missing documents.
- Reconcile the credit: Compare the amount received with the released payment.
Important Tips for Smooth Transactions
- Keep names consistent: Resolve mismatches between the banking and service accounts.
- Read the thresholds: Confirm the minimum, maximum and remaining daily allowance.
- Maintain a record: Keep receipts and support reference numbers together.
- Address document requests: Use the service’s verified upload channel when needed.
- Distinguish stages: Ask whether a delay concerns approval, release or bank receipt.
- Ask with a reference: Give support the payment identifier and receipt details.
- Check available funds: Avoid sending a sum that exceeds your planned budget.
Common Deposit and Withdrawal Amounts
| Transaction Type | Minimum Amount | Maximum Amount | Processing Time |
|---|---|---|---|
| PayID Deposit | $10 - $20 AUD | $5,000 - $10,000 AUD | Instant (under 60 seconds) |
| PayID Withdrawal | $20 - $50 AUD | $5,000 - $10,000 AUD | Example: 1–24 hours |
| VIP PayID Withdrawal | $50 AUD | $50,000+ AUD | Priority (under 6 hours) |
PayID Casino Security and Safety
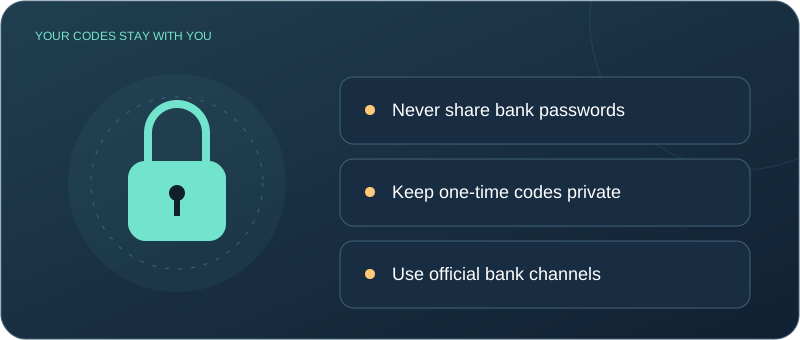
Payment security depends on several separate systems. Your bank protects access to its services, while an operator controls its own website, customer records and withdrawal process. Assess each part independently.
Banking-Level Security Features
These are the security details to examine rather than assuming every website provides identical safeguards:
- Protected session: Open banking services through the official app or website.
- Account authentication: Use the approval features your bank actually provides.
- Sensitive information: Never disclose banking passwords or one-time access codes.
- Recipient validation: Read the displayed payee name and investigate discrepancies.
- Activity alerts: Enable useful notifications and review unfamiliar payments promptly.
- Separate responsibilities: Assess the bank’s controls and the operator’s policies individually.
Choosing Licensed PayID Casinos
Treat a displayed badge as a starting point for checking, rather than proof on its own:
- Check the issuer: Verify any claimed licence against the relevant official register.
- Inspect the connection: HTTPS protects transport but does not prove operator credibility.
- Verify test references: Check whether a testing badge points to a valid report.
- Look for controls: Find account limits and closure options before using a service.
- Read the policy: Locate understandable withdrawal and promotion conditions.
- Compare evidence: Look for consistent records rather than anonymous praise alone.
Red Flags to Avoid
Pause and investigate when a service displays any of these warning signs:
- Warning: A claimed licence cannot be independently located.
- Warning: An offer conceals important eligibility conditions.
- Warning: Repeated complaints describe unresolved payment requests.
- Warning: Cashout rules are inaccessible or contradict one another.
- Warning: Support avoids specific questions about a transaction.
- Warning: Someone requests your banking password or approval code.
- Warning: You are urged to transfer immediately without checking details.
Protecting Your Personal Information
Good account habits remain useful whichever payment method a service lists:
- Unique access: Create a separate password for every account.
- Extra verification: Enable additional sign-in protection where available.
- Trusted device: Avoid entering financial credentials on shared or unfamiliar equipment.
- Current software: Apply security updates to your browser, device and banking app.
- Routine review: Compare statements with transactions you recognise.
- Authentic messages: Open the service directly instead of following unexpected login links.
- End the session: Sign out after using an account on a shared device.
Responsible Gambling with PayID
Bank statements can help make spending visible, but a fast payment option is not a substitute for a personal budget:
- Readable history: Use transaction records to total spending over a chosen period.
- Personal allowance: Decide on a spending cap before opening the cashier.
- Pause before payment: Recheck whether a transfer fits the budget you set.
- Bank controls: Ask your financial institution which payment restrictions are available.
- Available balance: Do not assume a payment method prevents debt or overspending.
If gambling is causing distress or financial pressure, consider pausing payments and speaking with your bank about available controls. The support website linked below offers a place to seek further information.
Frequently Asked Questions About PayID Casino
It is a descriptive label for a gambling website that lists PayID in its cashier. Check deposit and withdrawal support separately, since the presence of one option does not establish the availability of the other.
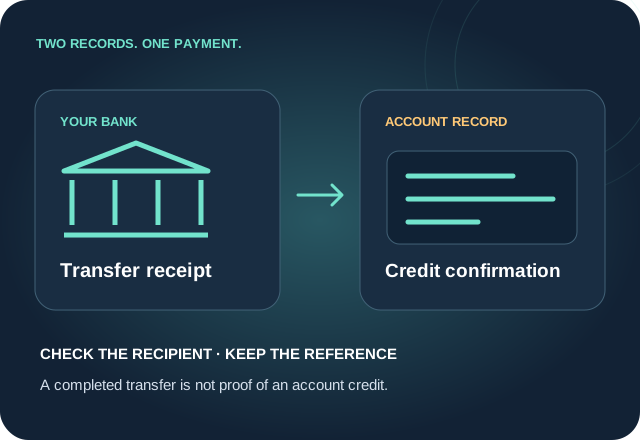
The bank transfer and the account credit are separate events. Review the service’s stated processing window and retain the payment reference so support can trace a credit that has not appeared.
Overall timing depends on document checks, the operator’s approval queue and the transfer after release. An estimate should identify which stage it covers; first requests may require additional review.
Do not assume every payment is free. Read the bank account conditions, the receiving service’s payment policy and any currency-conversion terms before confirming the amount.
Availability depends on your financial institution and account. Look for PayID settings in your banking app or consult the bank’s own support information for the applicable options.
An identifier is a convenience feature, not a guarantee about the receiving website. Check the recipient, protect your authentication codes and investigate any unexpected request before authorising a transfer.
Only if the operator explicitly offers that withdrawal route for your account. Confirm the eligible identifier, minimum amount, verification requirements and any restrictions in the cashier.
Limits belong to the bank account and the operator’s payment policy. The examples in this article should not replace the actual minimum, daily cap or remaining allowance displayed for your transaction.
The identifier is managed through a participating bank account. A website may still have its own registration and verification requirements, which are separate from setting up the bank identifier.
Promotional eligibility is governed by the individual offer. Read payment exclusions, wagering conditions and cashout restrictions rather than assuming a particular deposit method unlocks a benefit.